
Letters to our investors
Every quarter we write to our investors about what moved in the market, how we’re investing through it and how we’re returning capital. We publish them here in full.
Dear investor,
As we mentioned in our last update, we’re laser-focused on delivering DPI from our early funds. Notably, in recent weeks, the acquisition of DroneDeploy by Procore has delivered a great outcome for our LPs and the company. It's also a clear illustration of how we approach growth-stage investing: we take a global view on which company will win a category, back that view with conviction and add value where we're genuinely positioned to. Our Portfolio Committee is working through a number of further liquidity opportunities across the early funds and we look forward to sharing more in future updates.
Three things moved in the last quarter of FY26 with direct consequences for how we invest and how we return capital: the funding of the AI build-out shifted off big tech balance sheets and onto credit markets, the model layer stopped being scarce and the exit window opened at the top end.
Underneath all three is the same pattern. The market is paying for what AI runs on and discounting what runs on it. That’s a defensible position while the plumbing is still being built, but it gets harder to hold once the water starts flowing and this quarter gave real evidence on when that might be.
Who’s paying for the build-out
Big tech stopped self-funding the build-out this quarter. Alphabet raised US$84.75 billion in the largest stock offering on record. SpaceX printed a US$25 billion bond a fortnight after listing and Apollo and Blackstone structured US$36 billion of chip-backed debt.
The reaction from the market saw stocks dip for both Alphabet and Tesla as their quarterly reports were underscored by heavy cash drain and concerns about climbing capex forecasts shaved roughly US$890 billion from the Magnificent Seven in late July. The build-out is also meeting physical limits: New York moved toward a pause on hyperscale data centres, US data centres are on track for a fifth of national electricity by 2035, and at home the RBA flagged the boom as a new pressure in the inflation fight.
We read this less as the AI bubble bursting and more about reaching the point in the cycle where discipline arrives and the building continues anyway. Demand is real and cloud growth is accelerating, but the open question is who foots the bill.
The US$1.5 trillion in AI infrastructure spend in 2026 needs roughly US$3 trillion of revenue to justify it. That gap won’t get closed by more capex. Someone had to build the plumbing before the water could flow and the build was always going to be front-loaded. But a trillion dollars a year eventually needs applications to earn it back. In the near term, that bill lands on application companies’ P&Ls, which is why we flagged managing token costs as an execution differentiator in our last letter. It’s what separates durable AI businesses from expensive ones.
That shift hasn't fully arrived yet, but the application layer is where ANZ builders have outperformed, and it's where we're most concentrated across the Airtree Fund IV and V portfolios, via investments such as Everlab (healthcare), Legora (legal), Haast (compliance), Letty (property), Lorikeet (customer support), Gridsight (energy), Kismet (disability and aged care), Constantinople (banking), Firmable (sales), Actuals (accounting) and many more.
The model layer stopped being scarce
Two things stood out amidst the drumbeat of releases.
The first is that the US government became a live variable in model access. The US export directive pulled access to Anthropic’s Fable 5 and Mythos 5 models in June citing national security concerns, before access was restored 19 days later. OpenAI slowed the roll out of GPT-5.6 at the ‘request’ of the government, with gated access given to roughly 20 government-approved organisations before its public release. Model access is now a policy variable, which makes multi-model resilience a board topic, not just an engineering preference. We’re raising it directly with the boards we’re on to reduce the concentration risk as well as manage token efficiency as a gross margin line. Both need active management rather than an annual review.
The second is that two Chinese labs shipped frontier-scale open-weight models. Alibaba's Qwen 3.8 comes close to matching frontier performance at roughly a tenth of the price, and Moonshot AI's Kimi K3 posted very strong coding and reasoning benchmarks. Research theatre aside, the commercial reality is open models now handle about 65% of the work on the largest routing platforms, and the share of spend going to the closed US labs fell from 97% to around 83% inside a month.
Cost is already moving where inference happens, capability is close enough that scarcity is a weakening moat and both make the point that differentiation is shifting to the application layer.
Valuations run hot and cold
The Bessemer Cloud Index kicked back into gear over the last three months, rising 19.8% while the NASDAQ gained 0.6% and the S&P 500 3.4%. Chipmakers did most of the heavy lifting and now represent nearly a fifth of the S&P 500, while the Magnificent Seven trade at their lowest forward price-to-earnings ratio since ChatGPT launched.
Software remains the market's least favourite sector. Thirteen of the twenty worst performers in the S&P 500 this year are software and services companies, including Intuit, Workday, Adobe and Salesforce. Public SaaS growth has started to reaccelerate and the Bessemer Cloud Index forward revenue multiple hit 6.55x in June, but that's a handful of names moving the average rather than a sector recovering. Our read on the public markets hasn't changed: the market pays for quality and AI credibility.
Private markets are running hotter. The median US late-stage round is now exactly US$100 million and valuations are moving at speeds we haven't seen since 2021: insurance tech company Corgi doubled its valuation, from US$1.3bn to US$2.6bn, in three weeks after closing its previous round. Capital concentrated into mega rounds at both ends: 70% of Australian dollars went into two deals, Firmus' $725 million strategic round and Airwallex's $460 million Series H, while OpenAI and Anthropic absorbed 73% of all US capital raised in the first half.
Two things follow. Price discipline matters most exactly when the market abandons it. And the widening gap between the companies everyone is chasing and everything else is where patient, disciplined entry points come from. At the early stage in particular, we continue to take a ten-year view. Our approach is not to make momentum investments with the goal of a near-term sugar-hit markup. We're investing with first principles thinking, reasoning through business model evolution and long-term durability. The same discipline applies to existing marks. As we wrote last quarter, we’re watching this recalibration for both new investment pricing and material portfolio holding marks and will continue to adjust with a conservative bias.
The IPO window is ajar
Two listings at the top end don't make an open window, but they're the first real marks in a while. The path to get there wasn’t linear for either company; both weathered periods of slow growth and public scepticism before their eventual outcomes.
SpaceX's mid-June IPO raised US$75 billion at a US$1.75 trillion valuation, which tells us private markets can now incubate multi-trillion-dollar companies before they ever list. That outcome is partly a product of sovereign priority; governments treating national security, technological control and infrastructure independence as things worth funding directly rather than buying off the shelf. It's the same logic underwriting our theses in Advanced Navigation and HEO Space.
While it’s hard to compete with the SpaceX figure, Bending Spoons' NASDAQ debut at US$18.4 billion, up from an US$11 billion private valuation in October 2025, matters for different reasons. Its roll-up strategy shows that companies with moderate or inconsistent growth can still be valuable if they're capital efficient and use AI for operational leverage. We have a related thesis behind our investment in Kismet and others. As we flagged last quarter, that's the playbook we're working through with portfolio companies in the Active Management quadrant.
Dear investor,
We’re in the midst of a genuinely unusual moment. The macro environment, business models and labour markets are all in flux and that makes it difficult to predict with confidence what lies ahead. In times like these, history can be instructive.
Looking back at prior platform shifts, we see a consistent pattern. During the internet, mobile and cloud eras, the majority of cumulative enterprise value was created by companies founded in years four and five of the cycle. ChatGPT launched in November 2022, so we’re entering that window now.
That context matters because there’s no shortage of commentary declaring the end of software as we know it. The SaaSpocalypse narrative has taken hold, collapsing a complex moment into a single story of decline. We think that’s the wrong frame.
There are real pressures ahead for companies that don’t adapt and it would be remiss of any VC to pretend otherwise. But between historical patterns and what we’re seeing on the ground, this is one of the best moments in a decade for founders to start companies and VCs to deploy capital.
In that spirit, here’s what we’re seeing on the ground from where AI stands right now, to the risks we’re watching closely, how we’re investing in this environment and what’s happening to valuations.
Where AI is at right now
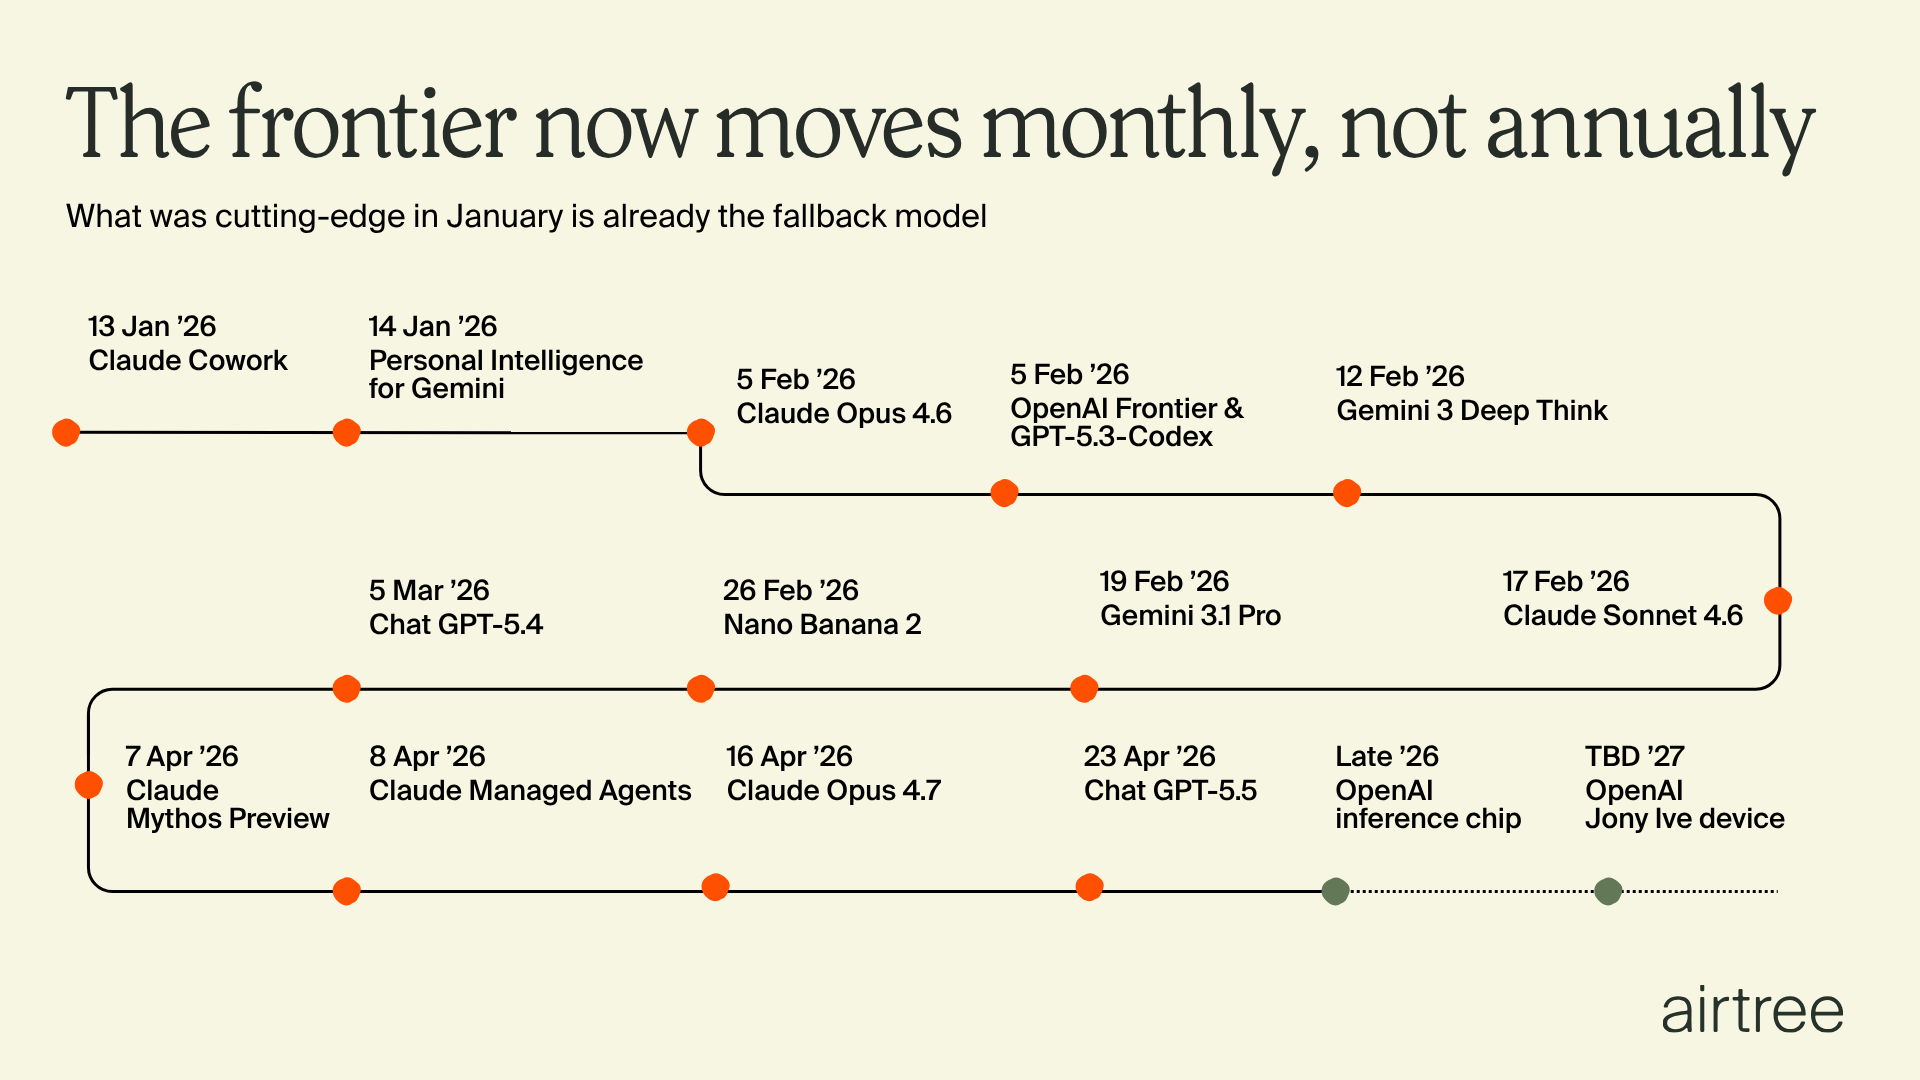
For founders building on top of foundational models, the window between “cutting edge” and “table stakes” is shrinking fast. Base models are becoming more interchangeable with every release cycle. Between writing this and pressing send, the landscape will have shifted again, as you can see from the constant drumbeat of releases this year already.
The market has moved past the experimentation phase. The race to launch AI features has evolved into something harder: building AI into sustainable, commercially sound products. We’re seeing the gap widen between companies that nail this and those that don’t. Execution matters and it comes down to deploying AI into production reliably, managing token costs thoughtfully and embedding it into customer workflows in a way that makes it hard to live without.
Notably, in Q3 FY26, Anthropic hit $30bn in ARR (with some analysts suggesting the figure has since surpassed $44bn in May 2026), outpacing OpenAI’s $25bn in ARR. Anthropic also built its most capable model yet—Claude Mythos—then withheld it from public release due to national security concerns. It’s now locked inside a closed consortium of 11 companies, used solely for defence, to find and patch the holes before bad actors can.
While Anthropic’s team were in town recently, we hosted a session for our AI founders with Amol Avasare, Head of Growth, and a dinner for top execs with Angela Jiang, Head of Product and Katelyn Lesse, Head of Engineering. They have been using Mythos internally since February and described its capabilities as a meaningful step beyond Opus 4.7. Suffice to say, progress is not slowing down.
The risks - named plainly
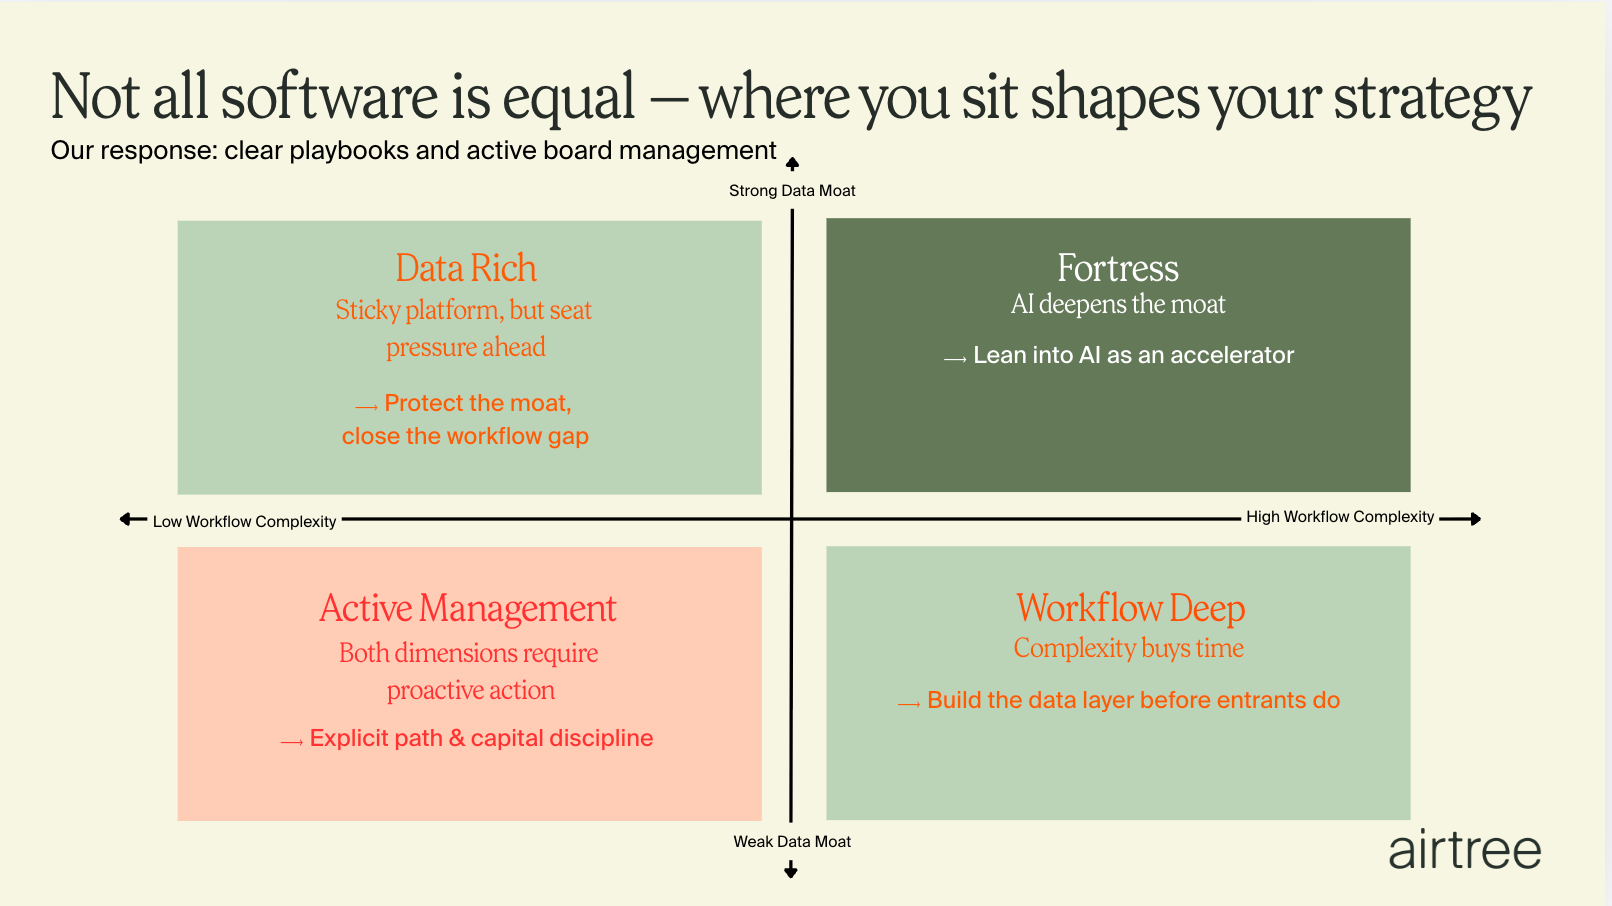
AI is creating structural winners and losers in software and the impact is uneven. How we think about whether AI is a headwind or tailwind for a company depends on their:
- Workflow complexity: How hard is it for an AI agent to safely replace the workflow?
- Data moat: How replaceable is the data advantage if an AI-native entrant appears?
We’re also mindful of the risk that frontier model providers moving up the stack poses - from infrastructure into application layer territory - which we’re already starting to see with Claude’s Legal Plugin that was announced in February and Claude Design, which launched in April. So far, this push has been concentrated on horizontal categories - one of the reasons our thesis leans into verticalisation (see further below).
Our current view is that the majority of Airtree NAV sits in AI-resilient positions. But our level of certainty is low given the pace of change; how long they remain resilient depends on how quickly they move to further embed their workflows and data moat.
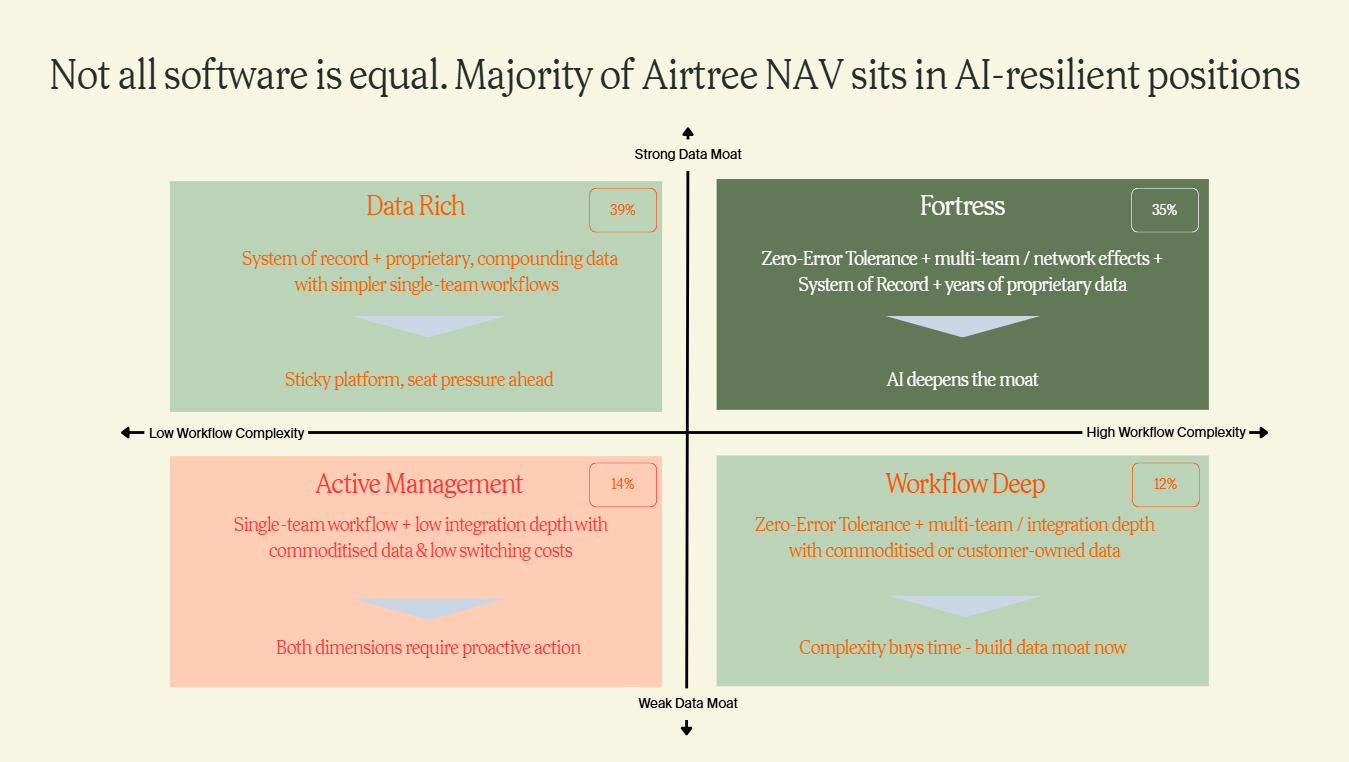
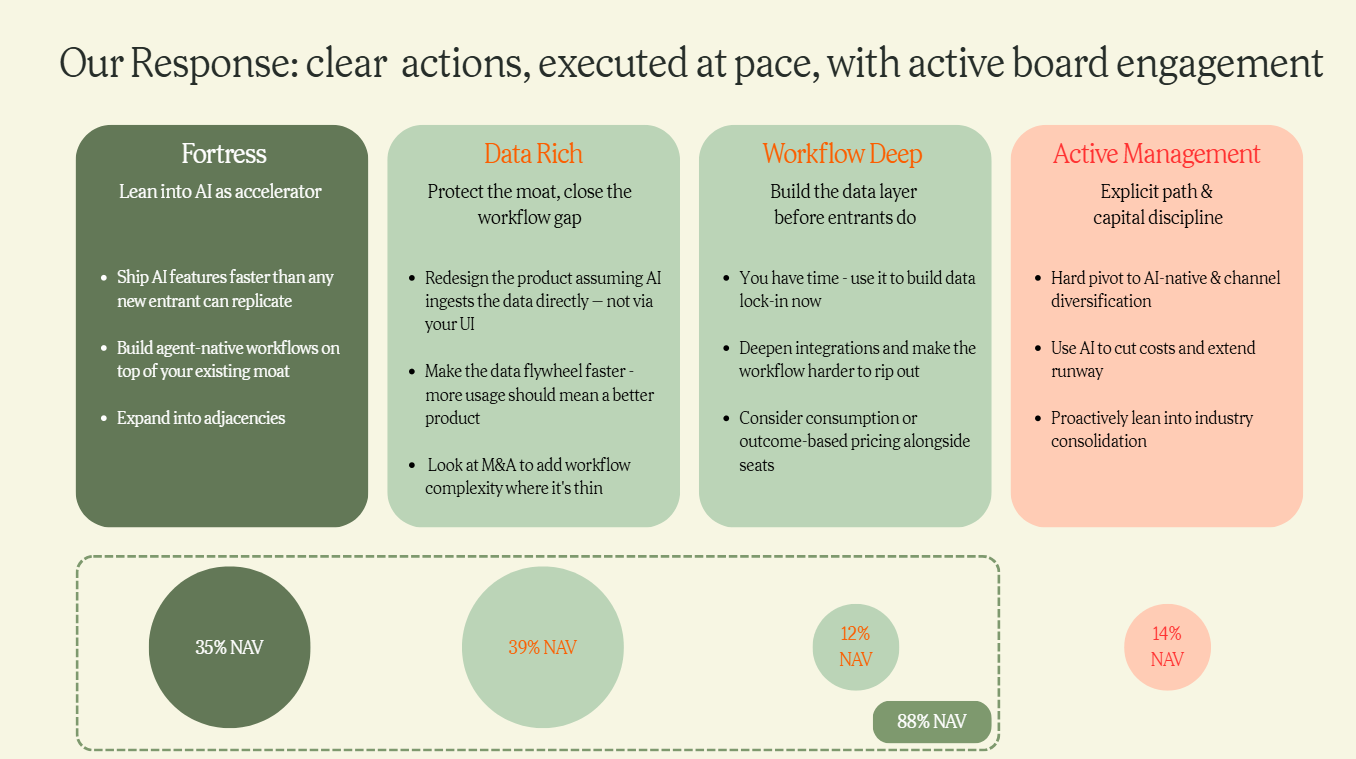
As is the game with a portfolio of investments, we have some companies that require us to lean in and work on an explicit path and capital discipline to mitigate pressure and its impact on valuations. The shape of that work varies materially by quadrant. This is a key focus of the firm.
How we’re investing in this environment
Understanding the environment shapes how we deploy. We're predominantly focused on 1) AI-native teams that can move at 10X the speed of other teams, and 2) vertical AI applications; companies that go deep on a specific workflow, industry, or customer set, rather than trying to be everything to everyone. We think the winners in this cycle will be defined by the depth of their workflow integration and their ability to launch new products and extensions faster than ever before.
We're also actively challenging our own assumptions about what ANZ founders should build. Some of the most interesting companies we're looking at don't fit the conventional template. That's deliberate. When the platform is shifting this fast, pattern-matching to the last cycle is a liability.
Looking at our recent investments, the throughline is how great founders thrive in times like these. These founders are living on the bleeding edge, executing with pace and adapting to the rapidly changing market conditions. These investments include:
- Advanced Navigation’s $158m Series C
- Legora’s $50m Series D extension
- Kimia’s $7m Series A
- Haast $17m Series A
Valuations: what we’re seeing
The public market context is stark. Looking at Bessemer’s Cloud Index, the sell-off of software companies has been severe, falling -24.1% over the last quarter while the NASDAQ gained +0.7% and the S&P 500 gained +0.6%. The ~25-percentage-point underperformance gap signals the direct cause-and-effect of foundational model feature releases on public software stocks.
Public market valuation multiples have compressed significantly, resetting entry points. The average forward revenue multiple across the index now sits at 5.3x, with average revenue growth at 18.6%. In a risk-off environment, multiples compress faster for high-growth software companies and that appears to be playing out. We’re watching this recalibration for both new investment pricing and portfolio valuations.
The private market dynamic is equally striking. 86% of US companies with $100m or more in revenue are private. The late-stage private market has effectively become the new public market. The value of the big three in the IPO pipeline—SpaceX, OpenAI and Anthropic — will exceed the collective value of every IPO over the last ~20 years, which should give everyone pause for thought.
There’s extreme dispersion on Bessemer’s Cloud Index and a few names are dominating the upside. Palantir stands out as an outlier, holding the top revenue multiple (56.4x), the top revenue growth rate (70%), and the top efficiency score (107.3%). Other leaders include Cloudflare and ServiceNow at the top of the forward revenue multiple rankings. This wide spread between top- and bottom-quartile companies means broad exposure to SaaS is punishing right now, and quality and differentiation matter more than ever for portfolio construction.
Closer to home, Atlassian’s 25% single-day rally on May 1, off the back of an AI-native reframing and accelerating cloud growth, is the starkest recent example of this divergence and of how sensitive the market and investors are the companies’ responses to the AI impact question.
The fact that pure-play SaaS is being punished while AI-differentiated names hold up suggests a narrative shift is underway. We are pressure-testing whether our portfolio companies have a credible AI story, not as marketing, but as a genuine product and revenue driver. If the answer is no, that’s a strategic gap that needs to be addressed quickly.
Returning capital in this environment
All of the above is impacting our ability to release DPI. Buyers are risk-off, multiples are compressed and exit processes are taking longer.
That said, we’re still actively progressing a strong pipeline of opportunities across two categories:
- Our older vintages (2014-2019)
- Companies where AI presents a structural risk.
For the older vintages, the work is hands-on: preparing businesses for exit, appointing advisors, engaging potential acquirers early and exploring creative paths to liquidity where a straightforward sale isn’t the obvious outcome, including mergers, RTOs, company buy-backs, partial liquidity and acqui-hires.
We’re deliberately holding our tier 1 and AI-resilient positions in these vintages.The bid for category leaders will be materially better when the market recognises the winners from the losers. In parallel, we’re ensuring they are preparing for exit and maintaining active conversations that could help accelerate the process.
For companies where AI is a structural headwind across vintages, we’re prioritising early action. Our guidance is to lean hard into AI across both product and operations, use efficiency gains to strip costs and get to cash flow breakeven. At the same time, we’re actively working through exit options, including trade sale, industry consolidation or acqui-hire. In these situations, waiting is unlikely to improve the outcome.
None of this is a forecast and the next 12 months are difficult to call. What we can tell you is how we’re spending our time.
We’re investing into outstanding founders and AI-native teams with conviction. The founders we’re meeting now are treating uncertainty as an advantage incumbents can’t match. We’re leaning into supporting the portfolio, being honest about which positions need an explicit path and getting creative about liquidity where a clean exit isn’t on the table. And we’re holding our category leaders deliberately because the bid for quality will be better once the market sorts winners from losers.